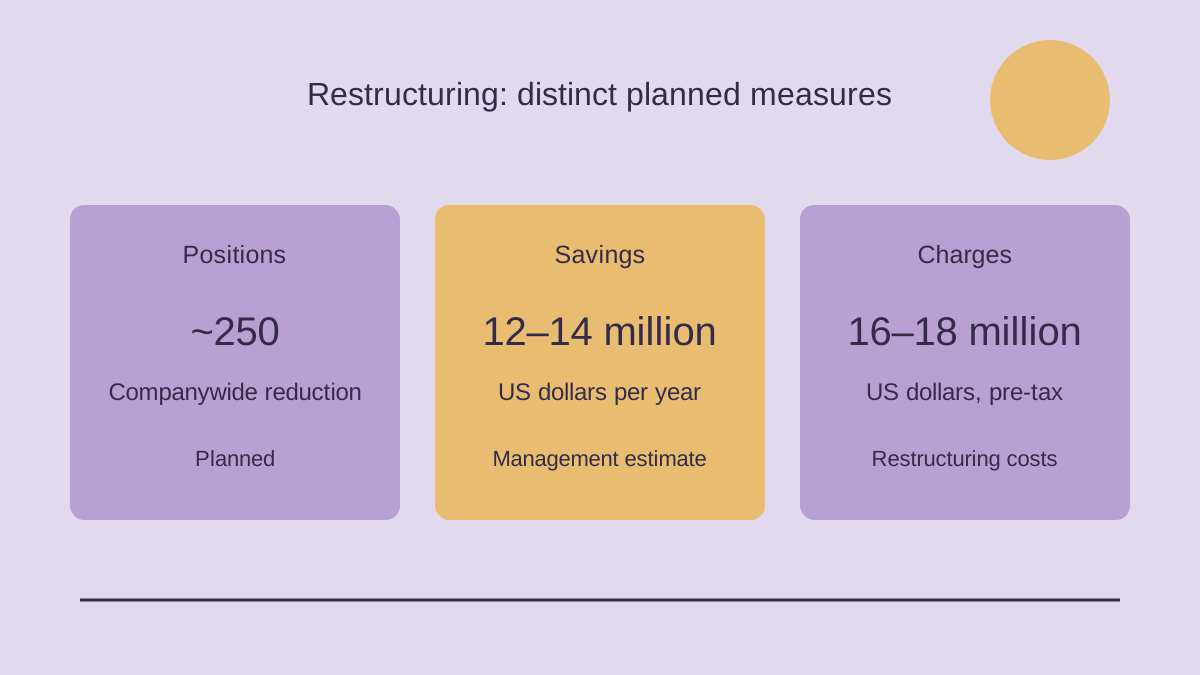
Apogee Enterprises plans to close its leased facility in Walker, Michigan, as part of a restructuring that would remove about 250 positions across the company. Manufacturing Dive reported on 9 February 2024 that production would move to Monett, Missouri, and Wausau, Wisconsin. The number of jobs affected applies to the wider business rather than solely to the Walker site.
A smaller operating structure
The manufacturer of architectural building products calls the programme Project Fortify. Its January announcement outlines changes to the architectural framing systems business, including a single operating entity and a simpler brand and commercial structure. Some lower-margin products and services would be withdrawn. Other measures cover architectural services and corporate operations.
The company expects annual savings of $12 million to $14 million, alongside approximately $16 million to $18 million in pre-tax restructuring charges. These are management estimates. They describe different financial measures: recurring savings on one side, implementation costs on the other.
What the transfer involves
- Walker would cease production under the announced plan.
- Two existing sites would receive the transferred work.
- Job reductions would extend beyond the closing facility.
- The proposed savings would emerge as the restructuring progresses.
A production transfer and a workforce reduction therefore need to be followed separately. Moving work to another plant does not by itself establish how many employees will transfer with it. Likewise, a companywide reduction cannot be read as the headcount of one factory.
The figures to watch
For readers assessing the plan, the practical distinction is between an announced operating arrangement and its execution. A receiving plant must take on the work before consolidation can be considered complete. Delivery continuity and the timing of restructuring charges are relevant measures of that transition; they cannot be inferred from a savings target alone.
The financial comparison also needs a consistent period. An annual savings rate cannot simply be subtracted from a one-time charge to describe the immediate earnings impact. Actual expenditure, the portion of savings achieved and the date production changes take effect would provide a clearer picture. As of this report, those results remain separate from the restructuring announced for the business in the United States.
Sources: Manufacturing Dive; Apogee Enterprises, SEC filing.
Leave a comment